Posted by:
Admin
Date:
December 12, 2025
Category:
blogs
Paying Tax On Rental Income
For many UK landlords, rental income is an important source of income. HMRC reports that 2.4 million landlords declared property income in the 2022/23 tax year. Rental income is generally taxed based on the profit from your property business rather than the total rent you receive. A basic calculation is:
Rental income – allowable expenses = taxable rental profit
The calculation can become more complex when you consider different types of expenses, mortgage finance costs, property allowances and your other taxable income. This guide explains how rental income is taxed, which expenses you may be able to claim, how to report and pay the tax and what landlords need to know about Making Tax Digital.
Key Takeaways
- Rental income is taxable, but tax is calculated on your rental profit, not your total rent received.
- Allowable expenses can reduce your taxable property profit.
- Property income is considered alongside your other taxable income.
- The £1,000 Property Allowance may benefit those with small amounts of qualifying property income.
- Residential landlords generally cannot deduct mortgage interest as an ordinary expense, but qualifying finance costs may provide a basic-rate tax reduction.
- Making Tax Digital for Income Tax is being introduced in stages based on qualifying income.
Do You Have to Pay Tax on Rental Income?
Yes. You may have to pay tax on rental income if you receive taxable income from letting out property. The amount you pay depends on your property income, allowable expenses, other taxable income and the tax allowances that apply to you. Your rental profit is considered alongside other taxable income, such as employment income, pension income or self-employment profits. This can affect the Income Tax band that applies to some or all of your rental profit.
Different rules may apply depending on your circumstances, including:
- renting out a room in your home
- jointly owned property
- property owned through a company
- small amounts of property income
- UK and overseas property
What Counts as Rental Income?
Rental income is not limited to the rent a tenant pays for using the property. Depending on the letting arrangement, your property income may also include certain payments you receive for services, furniture or other facilities connected with the property.
Examples of amounts that may form part of your property income include:
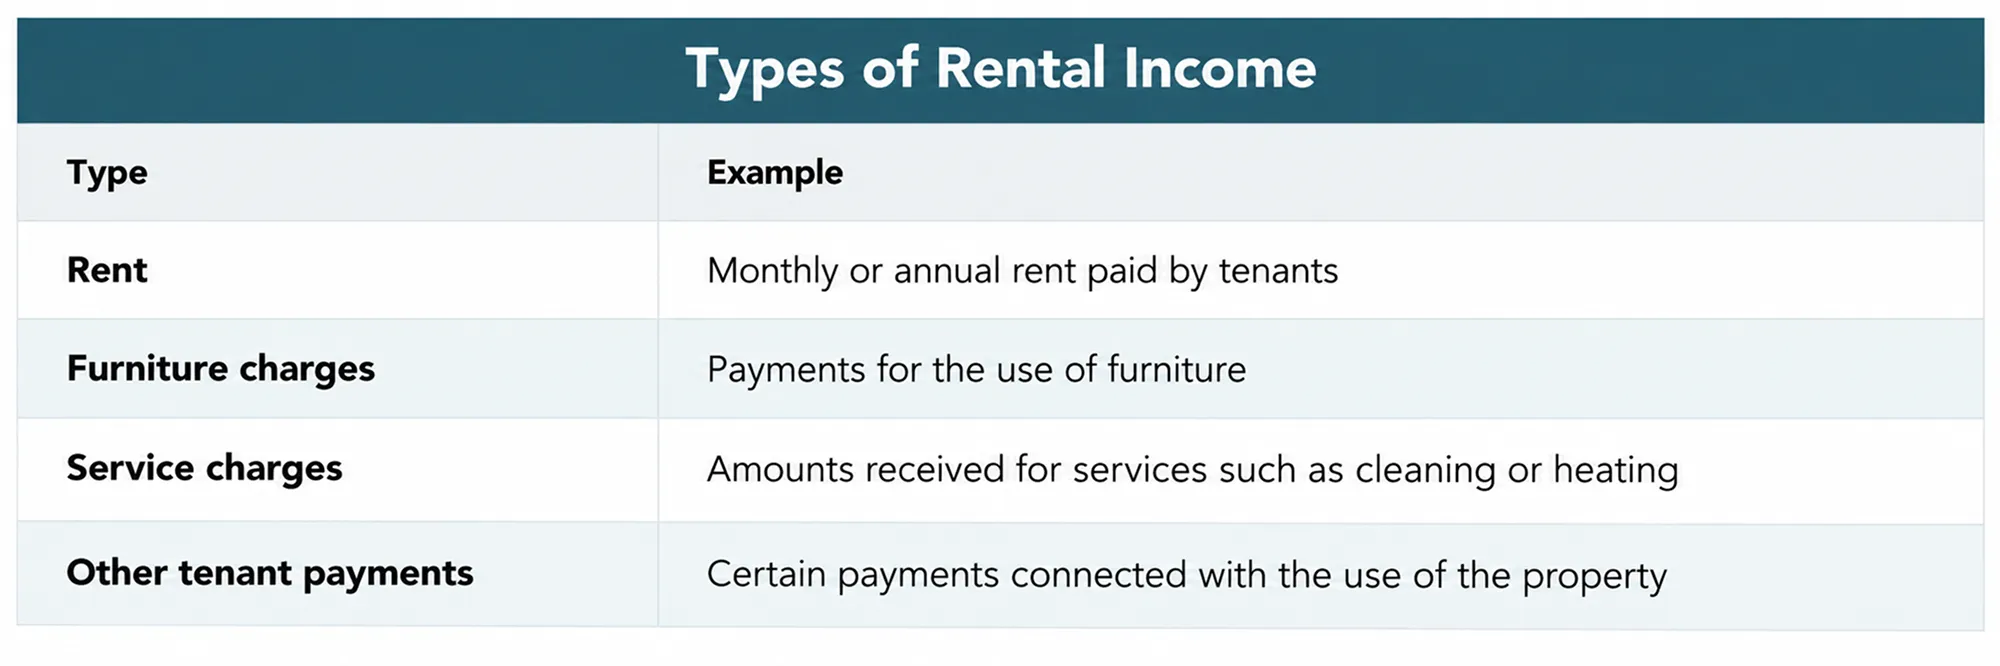
The exact treatment depends on the nature of the payment and the letting arrangement, so landlords should check the relevant HMRC rules when calculating their property income.
How Much Tax Do You Pay On Rental Income?
The amount of Income Tax you pay on rental income depends on your overall taxable income. Your property profit is generally considered alongside income from employment, self-employment, pensions and other taxable sources when determining which tax bands apply.
For 2026/27, the main Income Tax rates for England, Wales and Northern Ireland are:
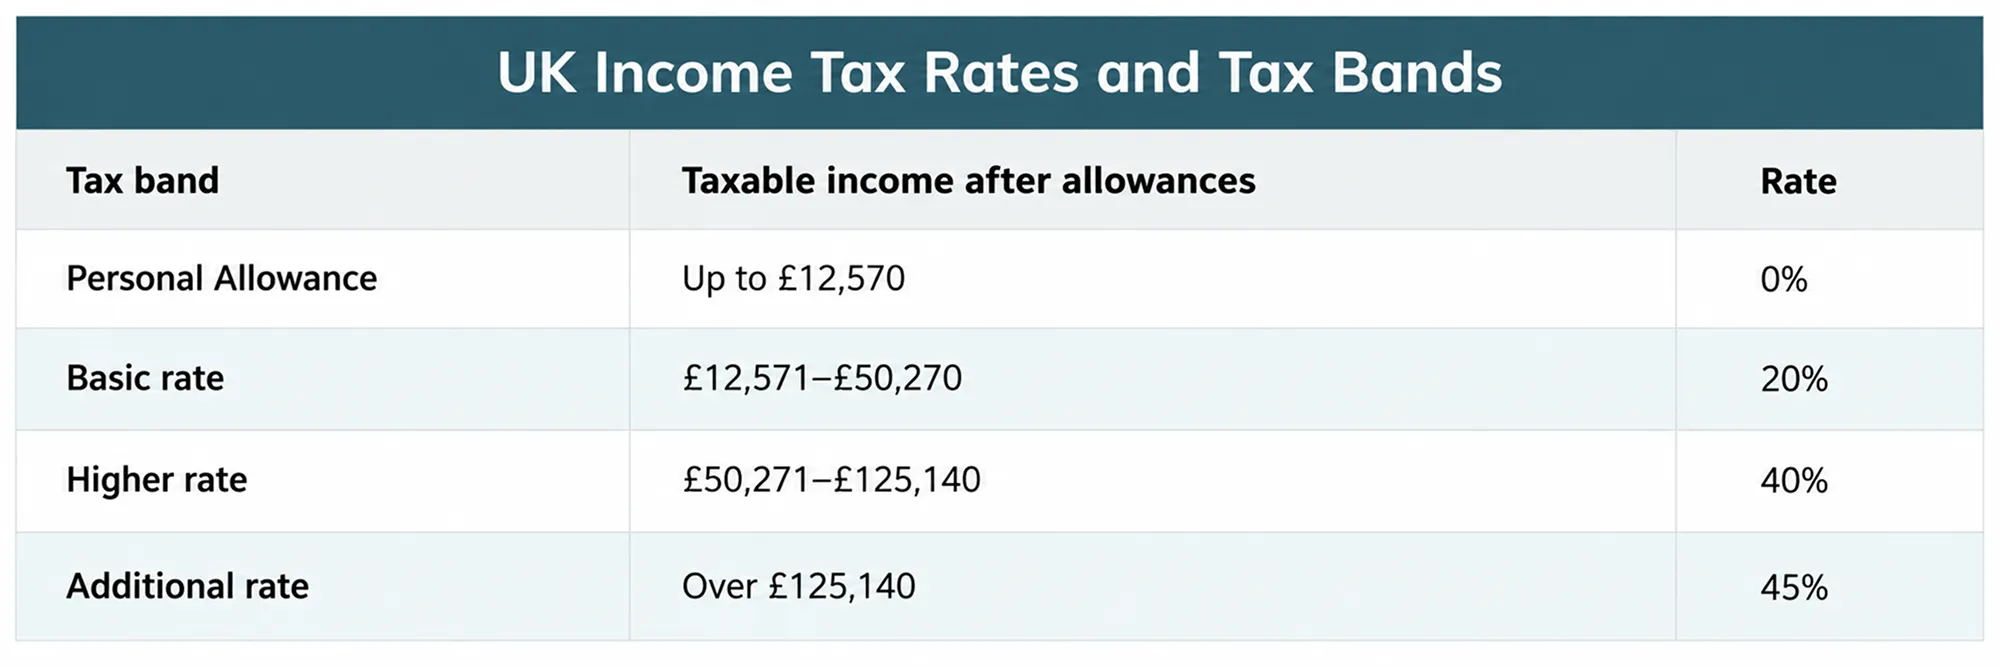
The standard Personal Allowance is £12,570, although it can be reduced for people with adjusted net income above £100,000. Scotland has different Income Tax rates and bands.
Example of How Rental Profit Can Be Taxed
Suppose a landlord has £25,000 of taxable employment income and £10,000 of rental profit. Their combined taxable income is £35,000. Assuming the standard Personal Allowance has already been accounted for in the figures above, the £10,000 rental profit falls within the basic-rate band and would be subject to Income Tax at 20%:
£10,000 × 20% = £2,000
This is a simplified example. The actual tax position can differ depending on the landlord’s Personal Allowance, other income, tax reliefs and individual circumstances.
This is also why two landlords with the same rental profit can have different tax bills. Their other income and available allowances may place their rental profit in different tax bands.
What Expenses Can You Deduct From Rental Income?
You can generally deduct expenses that are incurred wholly and exclusively for your property rental business, provided they meet HMRC’s rules for allowable expenses. Revenue expenses may reduce the profit on which your property business is taxed. Common examples include:
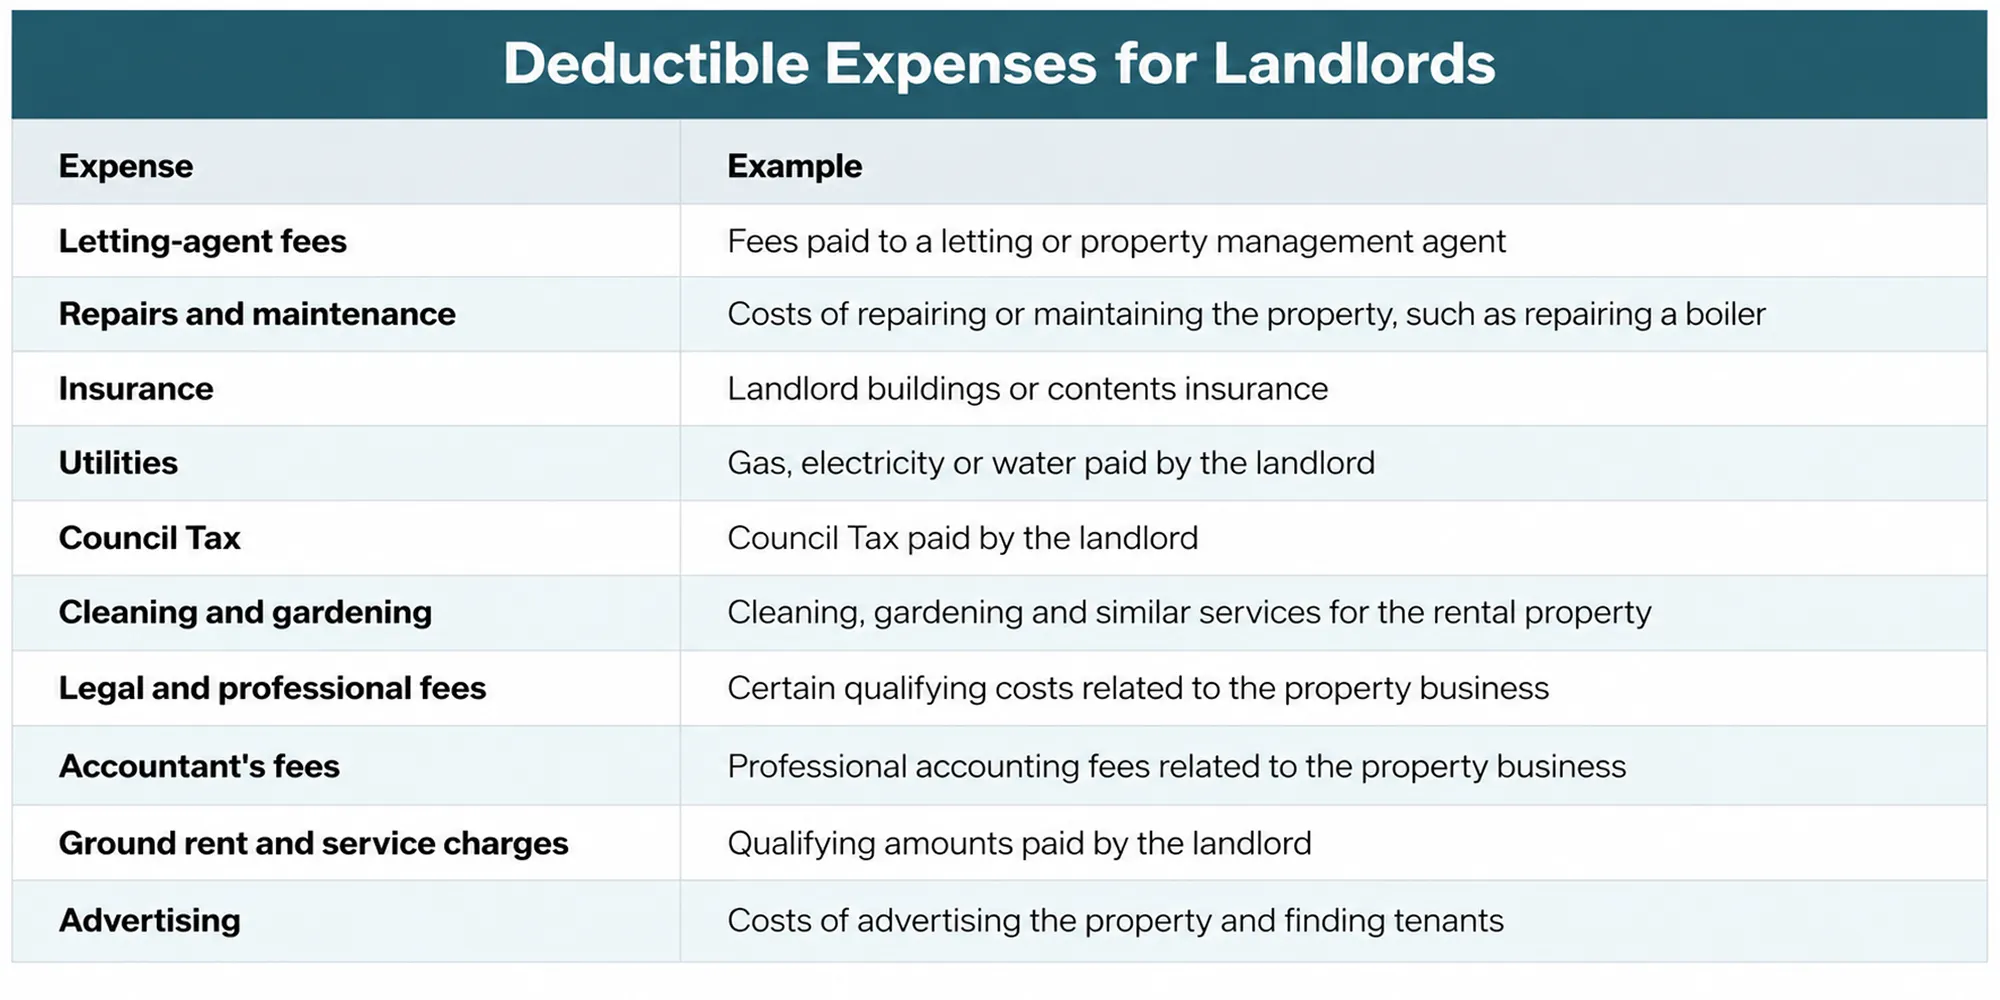
However, some property costs cannot normally be deducted as ordinary revenue expenses. These may include:
- the purchase price of the property
- the cost of adding an extension
- capital improvements or upgrades
- the capital element of mortgage repayments
- private expenses unrelated to the property business
Repairs vs Improvements
It is important to distinguish between repairs and improvements. A repair generally restores an existing part of the property to its original condition. An improvement usually changes or upgrades the property beyond its original condition and is more likely to be treated as a capital cost.
Capital expenditure is not normally deducted from rental income as an allowable revenue expense. However, certain capital costs may be relevant when calculating a future Capital Gains Tax liability, depending on the circumstances. Keep records and receipts for significant property costs even when they cannot be deducted from current rental income.
How Do You Report and Pay Tax on Rental Income?
Once you have calculated your property income and allowable expenses, you need to determine whether you have to report the income to HMRC.
You generally need to report property income through Self Assessment if it is more than:
- £2,500 after allowable expenses
- £10,000 before allowable expenses
If your rental income is above £1,000 but does not exceed these thresholds, you should contact HMRC to find out how you need to report and pay the tax. In some circumstances, HMRC may be able to collect the tax through your PAYE tax code.
If you need to register for Self Assessment and did not already file a tax return, you generally need to register by 5 October following the tax year in which you had the income.
Step 1: Calculate Your Rental Profit
Add up your rental income for the tax year and identify the allowable expenses that relate to your property business:
Rental income − allowable expenses = property profit
If you own more than one UK rental property personally, HMRC generally treats the properties as one UK property business when calculating the overall profit or loss.
Step 2: Consider Your Other Taxable Income
Your rental income is not taxed separately from your other income. Hence, consider your other taxable income along with your rental profit to determine the tax bands that would apply to you. If your combined taxable income exceeds the set margins, some or all of your rental profit would fall within the basic, higher or additional rates.
Step 3: Report the Income
If you need to file a Self Assessment tax return, report your property income and relevant expenses on the return. If you do not normally file a tax return but need to register for Self Assessment, the usual registration deadline is 5 October following the tax year in which you had the income.
Step 4: Pay the Tax
The usual deadline for paying Self Assessment tax is 31 January following the end of the tax year. Depending on your circumstances, you may also have to make payments on account towards your next tax bill. It is therefore useful to calculate your expected tax liability during the year and set aside enough money to meet the payment deadlines.
What You Need to Know About Making Tax Digital (MTD)
Making Tax Digital (MTD) for Income Tax is being introduced in stages for landlords and other individuals with qualifying income above the relevant thresholds. It does not apply to every landlord immediately.
If MTD applies to you, you will generally need to use compatible software to keep digital records of your property income and expenses and send quarterly updates to HMRC. You will also need to complete the relevant end-of-year tax requirements and pay any tax due by the applicable deadline.
A key point is that MTD eligibility is based on qualifying income, not your final rental profit. Qualifying income is the gross income from property and self-employment before expenses and tax:
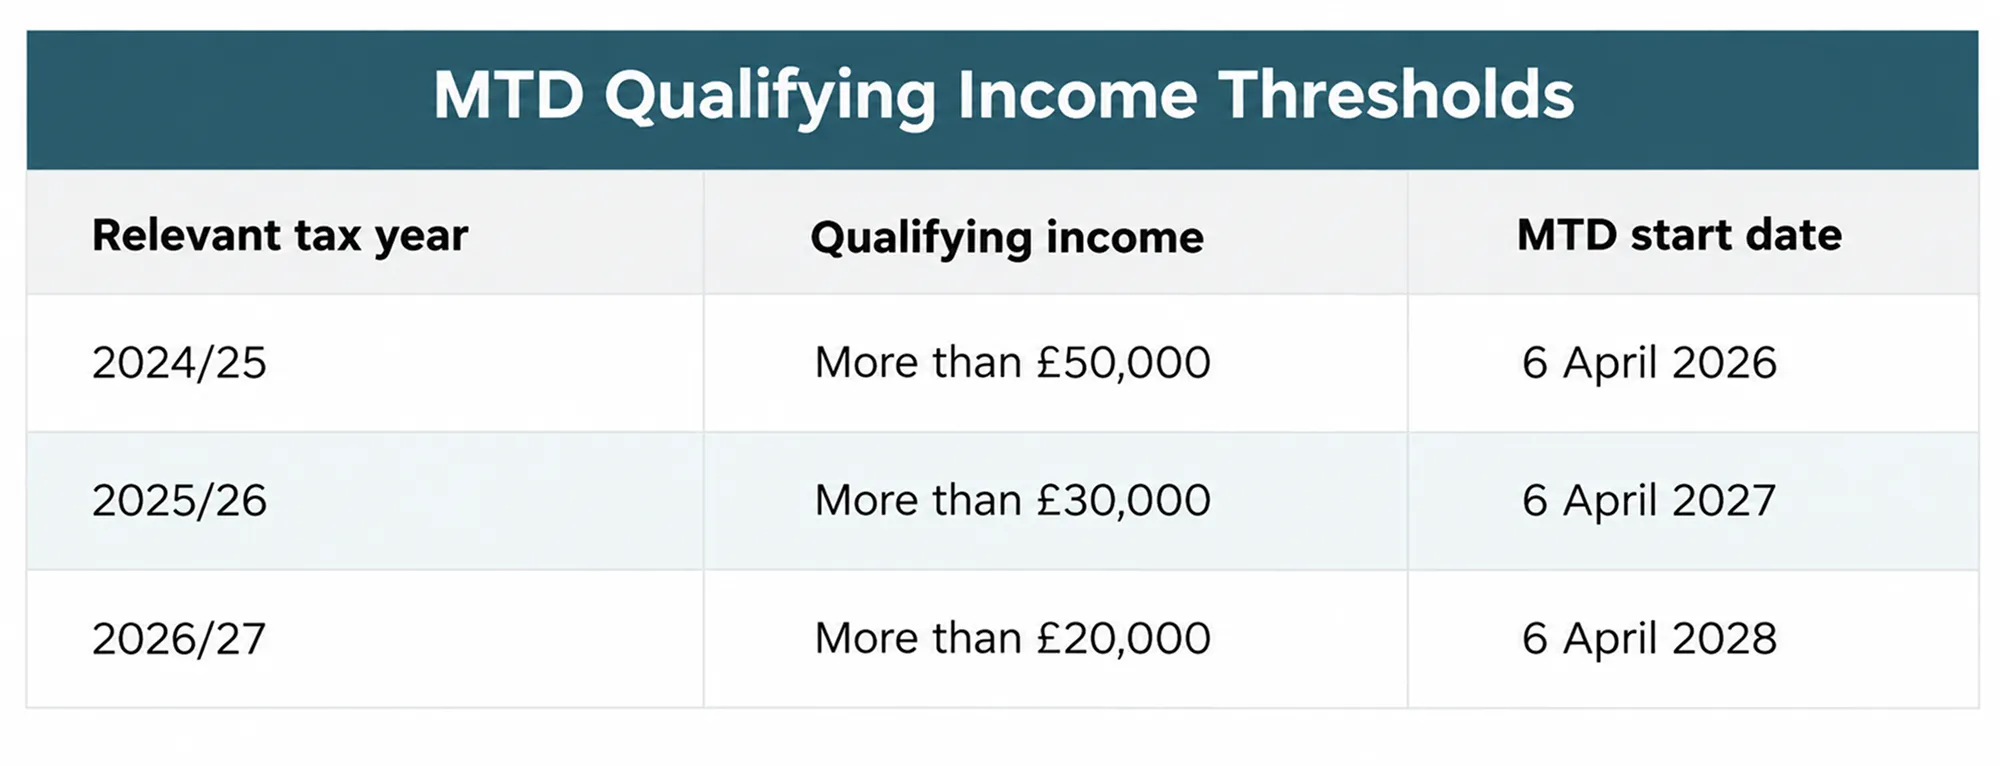
These thresholds apply to the relevant qualifying income, which can include both property and self-employment income.
Example
Suppose a landlord receives £25,000 in rental income, £10,000 in allowable expenses and £15,000 in rental profit. For MTD purposes, the relevant qualifying income is £25,000, not £15,000. Therefore, if the landlord’s qualifying income exceeds the applicable threshold for the relevant tax year, they may need to use MTD even though their final rental profit is lower.
MTD changes how qualifying taxpayers keep records and report their income. It does not change the basic calculation of rental profit or the Income Tax rates themselves.
Checklist: Records to Keep for Rental Income and MTD
Keeping organised records can make it easier to calculate your property profit, support expense claims and meet HMRC reporting requirements:
Rental Income
☐ Rent received from each tenant
☐ Bank statements showing rental payments
☐ Letting-agent statements
☐ Records of other relevant payments received from tenants
☐ Records for each rental property
Allowable Expenses
☐ Repair and maintenance invoices
☐ Insurance documents
☐ Letting-agent and management fees
☐ Utility and Council Tax records where applicable
☐ Legal and professional fees
☐ Advertising costs
☐ Ground rent and service-charge records
☐ Relevant finance and mortgage records
Property and Capital Costs
☐ Property purchase records
☐ Records of improvements and alterations
☐ Receipts for major capital work
☐ Records of relevant costs connected with a future property sale
MTD Records
If MTD for Income Tax applies to you, you should also:
☐ Use compatible software
☐ Keep relevant income and expense records digitally
☐ Keep supporting evidence for your figures
☐ Send quarterly updates by the required deadlines
☐ Complete the end-of-year tax requirements
☐ Keep your records for the required retention period
Conclusion
Letting a property in the UK can create Income Tax obligations alongside rental income. To work out what you owe, you need to understand which income and expenses count, how your property profit is taxed alongside your other taxable income and which rules apply to your circumstances.
You should also keep up with relevant rules on residential finance costs, the Property Allowance, losses and Making Tax Digital. Keeping accurate records throughout the year can make it easier to calculate your tax and meet your reporting obligations. Professional tax services can also help with rental income tax and HMRC requirements
Need Help With Rental Income Tax?
Sterling Cooper Consultants can help you manage rental income tax, prepare your Self Assessment and meet HMRC requirements. Contact us today to discuss your tax needs.
FAQs
Yes, you may. Your rental profit is generally considered alongside your employment income, which can affect the tax band that applies to it.
Ordinary rental income is generally not subject to National Insurance in the same way as employment or self-employment income. Different rules may apply in certain circumstances.
If your allowable expenses are greater than your rental income, your property business may make a loss. Property losses are generally carried forward and set against future profits from the same property business, subject to the relevant rules.
You cannot normally deduct the capital repayment element of a residential mortgage from rental income. Qualifying finance costs, such as mortgage interest, may instead qualify for a basic-rate tax reduction.
Generally, each owner is taxed on their share of the property income and allowable expenses. Different rules can apply to jointly owned property held by married couples and civil partners.
Recent Posts