Posted by:
Admin
Date:
September 7, 2026
Category:
blogs
Top Tax Saving Tips to Reduce Your Bill Legally
Could you be missing out on opportunities to save tax in the UK? The right tax-saving measures can help you keep more of your income. These may include claiming eligible tax reliefs, making pension contributions and using tax-efficient savings options, such as ISAs. Self-employed professionals and business owners may also be able to claim allowable business expenses.
In this guide, we explain practical tax-saving tips that can help you reduce your bill while staying within UK tax rules. If you need personalised guidance, you can also explore our tax planning and compliance services to understand your options and plan ahead.
Key Takeaways
- Pension contributions may qualify for tax relief and reduce adjusted net income.
- ISAs offer tax-free returns on eligible savings and investments.
- Allowable business expenses can reduce taxable profits for self-employed individuals.
- Gift Aid, Marriage Allowance and other reliefs may lower your tax bill if you qualify.
- Keep accurate records and review your tax position before the end of each tax year.
What Are the Top Tax Saving Tips?
You can potentially reduce your UK tax bill by using available allowances, claiming eligible reliefs and planning your finances carefully. Here are some options to consider.Maximise Pension Contributions
Pension contributions can help you save for retirement while receiving tax relief. Depending on your pension arrangement, contributions may reduce your adjusted net income or qualify for tax relief through your pension provider. Higher-rate and additional-rate taxpayers may be eligible for further relief. However, the amount depends on your earnings, pension scheme and applicable allowances. Check these limits before increasing your contributions.Reduce the Impact of the 60% Tax Trap
The 60% tax trap affects some taxpayers with adjusted net income between £100,000 and £125,140. Your £12,570 Personal Allowance is reduced by £1 for every £2 of adjusted net income above £100,000, leaving no allowance once income reaches £125,140. Eligible pension contributions and Gift Aid donations may reduce adjusted net income, potentially helping you retain more of your Personal Allowance. Review your position before the tax year ends to determine whether these options could help.Consider Salary Sacrifice
Salary sacrifice allows employees to exchange part of their contractual salary for an eligible benefit provided by their employer. Depending on the arrangement, this may reduce taxable employment income and National Insurance contributions. However, it can affect salary-linked benefits, statutory payments and pension calculations. Check the terms with your employer before agreeing to a change.Use Your ISA Allowance
An Individual Savings Account (ISA) allows you to earn eligible savings interest, dividends and investment gains without UK Income Tax or Capital Gains Tax on returns within the account. The overall annual ISA allowance is £20,000 for the 2026/27 tax year. You could use a Cash ISA for savings or a Stocks and Shares ISA for eligible investments, depending on your goals and attitude to risk. The allowance is individual, so review how much you have available before contributing. HMRC’s ISA guidance explains the main rules.Consider Business Asset Disposal Relief When Selling a Business
Business Asset Disposal Relief (BADR), formerly known as Entrepreneurs’ Relief, may reduce the Capital Gains Tax payable on qualifying business disposals. For qualifying disposals made on or after 6 April 2026, the relief applies a Capital Gains Tax rate of 18%. Eligibility depends on the type of disposal and the relevant ownership, trading and other conditions.
Pro tip:
Keep business and personal spending separate where possible. Clear records make it easier to identify genuine business costs and support your tax return.
Use Gift Aid for Charitable Donations
Gift Aid increases the value of eligible charitable donations when the donor meets the relevant tax conditions. The charity can reclaim 25p for every £1 donated. Higher-rate and additional-rate taxpayers may also claim further tax relief on qualifying donations. The examples below assume the donations qualify and the taxpayer can claim the additional relief:
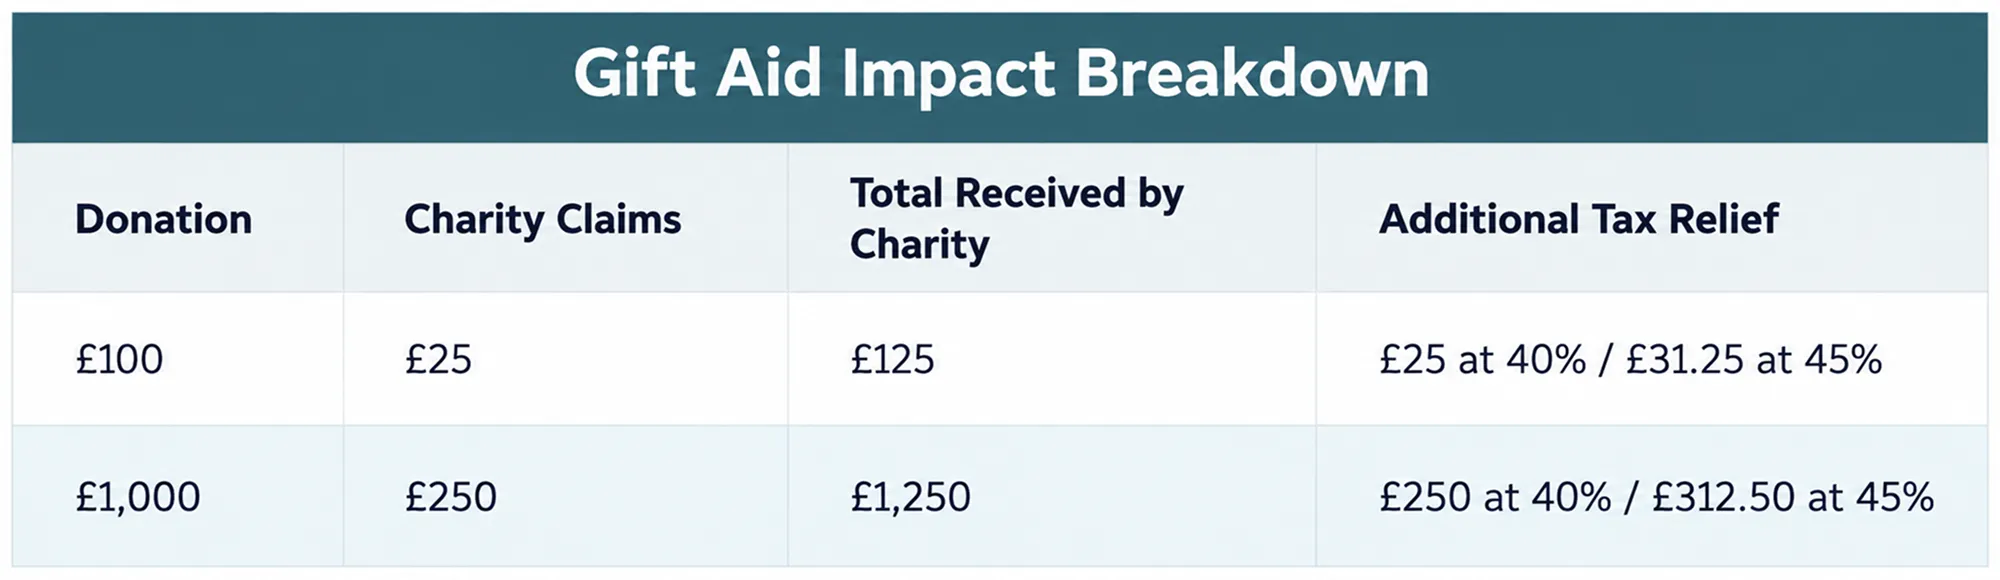
Gift Aid donations may also help reduce adjusted net income when calculating eligibility for certain allowances. Keep records of your donations and ensure you meet the relevant conditions.
Consider Enterprise Investment Scheme Relief
The Enterprise Investment Scheme (EIS) offers tax relief to eligible individuals who invest in qualifying smaller companies. Income Tax relief is generally available at 30% of the amount invested in qualifying shares, subject to the scheme’s conditions. For 2026/27, the maximum annual investment eligible for EIS Income Tax relief is generally £2 million. Investments above £1 million must be in qualifying knowledge-intensive companies. EIS investments carry significant risks and may be difficult to sell. Assess the potential for losses and the company’s prospects before investing.Claim Allowable Business Expenses
Self-employed individuals can reduce their taxable profits by claiming allowable business expenses. Depending on the business, these may include professional fees, insurance, office supplies and business travel. Costs must meet the relevant tax rules. If an expense covers both business and personal use, you may need to apportion the cost. Keep receipts, invoices and other supporting records to substantiate your claims.Pro tip:
Keep business and personal spending separate where possible. Clear records make it easier to identify genuine business costs and support your tax return.
Consider the Rent a Room Scheme
The Rent a Room Scheme allows eligible individuals to receive up to £7,500 a year in tax-free rental income from furnished accommodation in their main home. The threshold falls to £3,750 if the income is shared with another person.
If your receipts exceed the threshold, you may need to report the income and calculate your tax liability under the applicable rules. Check HMRC’s Rent a Room Scheme guidance to determine whether you qualify.
Check Your Eligibility for Marriage Allowance
Eligible married couples and civil partners may reduce their combined Income Tax bill through Marriage Allowance. It allows one partner to transfer £1,260 of their unused Personal Allowance to the other. The transferring partner must meet the relevant eligibility conditions, and the receiving partner must generally pay tax at no more than the basic rate. Check the current rules before applying.
Review Joint Savings and Investments
Couples may improve their tax efficiency by reviewing how savings and investments are owned. Interest and investment income can be taxed differently depending on each person’s income, available allowances and the type of investment. Any transfer must reflect genuine ownership and comply with the relevant tax rules. Consider the wider financial implications before changing ownership arrangements.
Make Use of Your Capital Gains Tax Allowance
Selling investments or other chargeable assets for a profit may trigger Capital Gains Tax (CGT). For individuals, the annual exempt amount is £3,000 for the 2026/27 tax year. You may be able to reduce taxable gains by using this allowance and deducting eligible losses. The timing of disposals can also affect your tax position, but decisions should reflect your wider financial goals.
Check the current CGT rules before selling assets, particularly if you are planning several disposals within the same tax year.
Conclusion
Reducing your UK tax bill legally starts with identifying the allowances, reliefs and tax-efficient options that apply to your circumstances. Pension contributions, ISAs, Gift Aid and allowable business expenses are useful starting points. Review your finances before the end of the tax year and keep accurate records to support your claims. Sterling Cooper can help you assess your tax position and plan your affairs through our taxation services, in line with current HMRC rules
Need guidance on your tax responsibilities?
Contact us to discuss your requirements and find the right support for your circumstances.
FAQs
Consider pension contributions, ISAs, allowable business expenses, Gift Aid and Marriage Allowance. The most suitable options depend on your income and financial circumstances.
Yes. Eligible contributions can qualify for tax relief and may reduce adjusted net income. The amount depends on your pension arrangement, earnings and applicable limits.
The overall annual ISA allowance is £20,000. Individual ISA types have their own rules, so check the applicable limits before contributing.
No. Relief is available only for qualifying investments and eligible investors. EIS investments can result in significant losses, so assess the risks before investing.
Eligible couples may benefit from the Marriage Allowance and review how savings and investments are owned. Any arrangements must meet the relevant tax rules.
Recent Posts